


Strategic Buyer or Private Equity? Choosing the Right Acquirer in Your Exit Strategy for Business
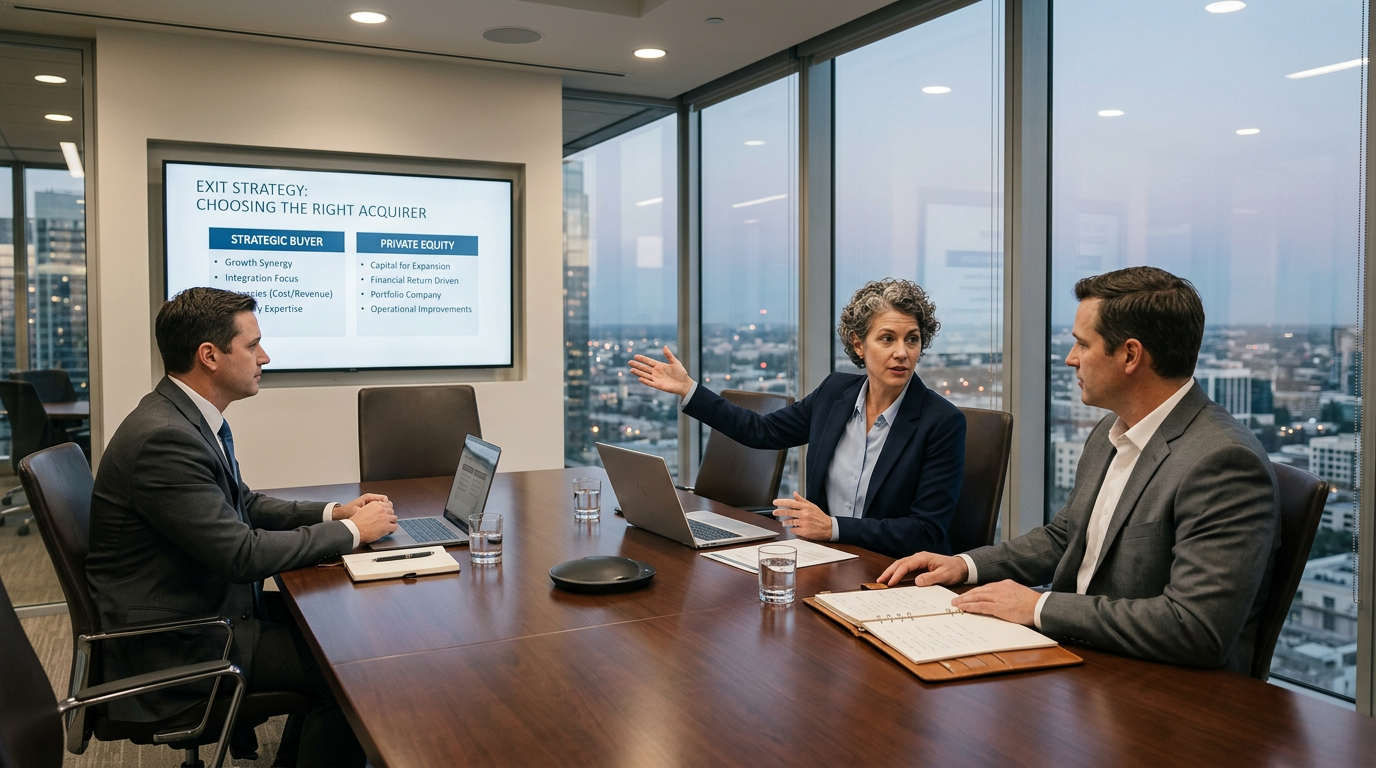
Once an owner decides to sell, the next question comes fast: who should buy it? For most middle-market companies, the realistic answer comes from two groups. One is strategic buyers, meaning operating companies in your industry or a related one. The other is private equity firms, which buy companies as investments.
Both can pay well. They just pay for different reasons, structure deals differently, and treat the business and its people differently once the deal closes. Choosing between them is one of the biggest decisions in an exit strategy for business, and it deserves to be made on purpose.
This article compares the two buyer types, explains how roll-ups have blurred the line between them, and lays out the questions that help owners pick the right fit for their exit strategy for business.
What strategic buyers want
A strategic buyer is an operating company that wants your business to strengthen its own. It might be a competitor, a supplier, a customer, or a company in an adjacent service line.
Strategic buyers usually value what your company adds to theirs. That might be new customers, a new geography, a capability they lack, or cost savings from combining operations. When those benefits are large, a strategic buyer can sometimes justify a higher price than a financial buyer, because it's paying partly for value it can only capture by owning you.
The tradeoff often comes after closing. Strategic buyers tend to integrate. Your brand may be retired. Back-office roles that duplicate theirs may be cut. Owners are often expected to stay for a defined transition period and then step away. For an owner ready to leave, that can be ideal. For one who cares deeply about the company's name and staff, it can be hard to accept.
What private equity firms want
A private equity firm buys companies with money raised from investors, aiming to grow them and sell again later. Holding periods often run several years. The firm needs the business to keep performing under its ownership, so it usually wants strong management to stay in place.
Private equity buyers commonly ask the owner to reinvest part of the proceeds as rollover equity. That keeps the owner invested in the next stage of growth. If the firm later sells the company at a higher value, the rolled equity can pay out a second time. Owners who believe the business has more growth ahead often find that structure appealing.
These deals also tend to use debt to fund part of the purchase. That can support a strong price, but it also means the new owner will watch cash flow, reporting, and financial controls closely after closing.
How roll-ups blur the line
In consolidating industries, the distinction is less clean than it used to be. Many private equity firms buy a larger platform company, then acquire smaller businesses to add onto it. Those add-on acquisitions often look a lot like strategic deals. The platform wants your customers, your technicians, or your territory, and it may fold your operations into its own.
For owners in sectors such as facilities, industrial, and professional services, this is a central part of building an exit strategy for business. A platform may pay well for a company that fills a gap in its footprint, and your business may be worth more to one platform than another depending on where each already operates.
Key differences at a glance
Every deal is different, but these patterns hold often enough to guide early thinking:
- Price drivers: strategic buyers pay for fit and cost savings, while private equity pays for earnings, growth potential, and management strength
- Payment structure: strategic deals more often pay mostly cash at closing, while private equity deals frequently include rollover equity
- Owner's role: strategic buyers usually want a shorter transition, while private equity often wants the owner or key managers to stay
- Employees: integration by a strategic buyer can mean overlapping roles are cut, while private equity typically keeps the team and adds resources
- Brand: strategic buyers may absorb it, while platforms vary in how much they keep
- Diligence: both run thorough reviews, but private equity buyers often focus heavily on financial quality and lender requirements
Questions to answer before you choose
The right buyer depends less on which type pays more in theory and more on what you want from the sale. Before talking to any buyer, get clear on a few things.
How long do you want to stay involved?
If you want to leave within a year, a strategic buyer or a full sale may suit you better. If you'd like to keep working and share in future growth, private equity may fit.
How much cash do you need at closing?
Rollover equity can pay off later, but it isn't cash today. If your financial plan depends on full proceeds now, structure matters as much as price.
What should happen to your people and your name?
Many owners care about this more than they expect to. If it matters to you, raise it early and weigh how each buyer approaches integration.
How much risk do you want to keep?
Earnouts, rollover, and seller notes all tie part of your payout to the company's future performance. Decide how much of that you're comfortable carrying.
You don't have to pick in advance
Owners sometimes assume they must choose a buyer type before starting a sale. In practice, a well-run process often approaches both. Contacting a curated group of strategic acquirers and private equity firms creates real competition, and competition is what improves price and terms.
It also gives you a live comparison. Seeing actual offers side by side, with their structures spelled out, is far more useful than guessing in the abstract. An owner who expected to sell to a competitor may find a private equity platform offering a better overall package, or the reverse.
Confidentiality matters here. Approaching competitors means sharing sensitive information with companies that could use it. A disciplined process controls what each buyer sees and when, releasing the most sensitive details only to serious bidders later in the process.
Look past the headline price
Comparing offers takes more than reading the top number. Look at what you receive at closing, what's deferred, and what's at risk. Review escrow amounts, the size and terms of any earnout, rollover percentages, working capital targets, and the employment or consulting terms that come with the deal.
Two offers with the same price can produce very different results once taxes, structure, and risk are counted. A sell-side advisor can model those outcomes so the comparison reflects what you actually keep, and can push back on terms that shift too much risk onto you.
Picking the right partner for the next chapter
Strategic buyers and private equity firms both buy good companies. The better question is which one fits your goals for money, timing, and legacy. Owners who define those goals early and test the market with both groups usually end up with more options and stronger terms.
Roadmap Advisors is a middle-market M&A advisory firm that runs sell-side processes for owners in consolidating industries. The team helps owners define their goals, reaches out discreetly to both strategic acquirers and private equity firms, and leads negotiation on price, structure, and terms through closing. Schedule a consultation to talk through which buyers fit your company.
 Deutsch
 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek